
Gold’s latest pullback offers a chance to buy a stronger business than the one investors owned a year ago. Royal Gold (RGLD) just cleared the debt tied to its acquisitions, giving its growing royalty and streaming portfolio more room to reward shareholders.
The stock's appeal is cash flow with fewer claims ahead of investors, though the price still calls for restraint.
The Debt Is Gone
Royal Gold’s Nov. 4 results showed $344.4 million in quarterly operating cash flow. It repaid its final $150 million of revolving debt on Oct. 19, less than a year after borrowings reached $1.225 billion following its acquisitions.
Management had initially expected repayment to take two years. By finishing early, it frees cash for new investments, dividends, and buybacks without first having to service the debt.
Royal Gold's royalty and streaming contracts give it exposure to mine output without making it the mine operator. As our streaming-versus-mining comparison explained, that can limit direct exposure to rising mining expenses. Still, production delays at partner mines can reach shareholders.
The Price Tag Has a Limit
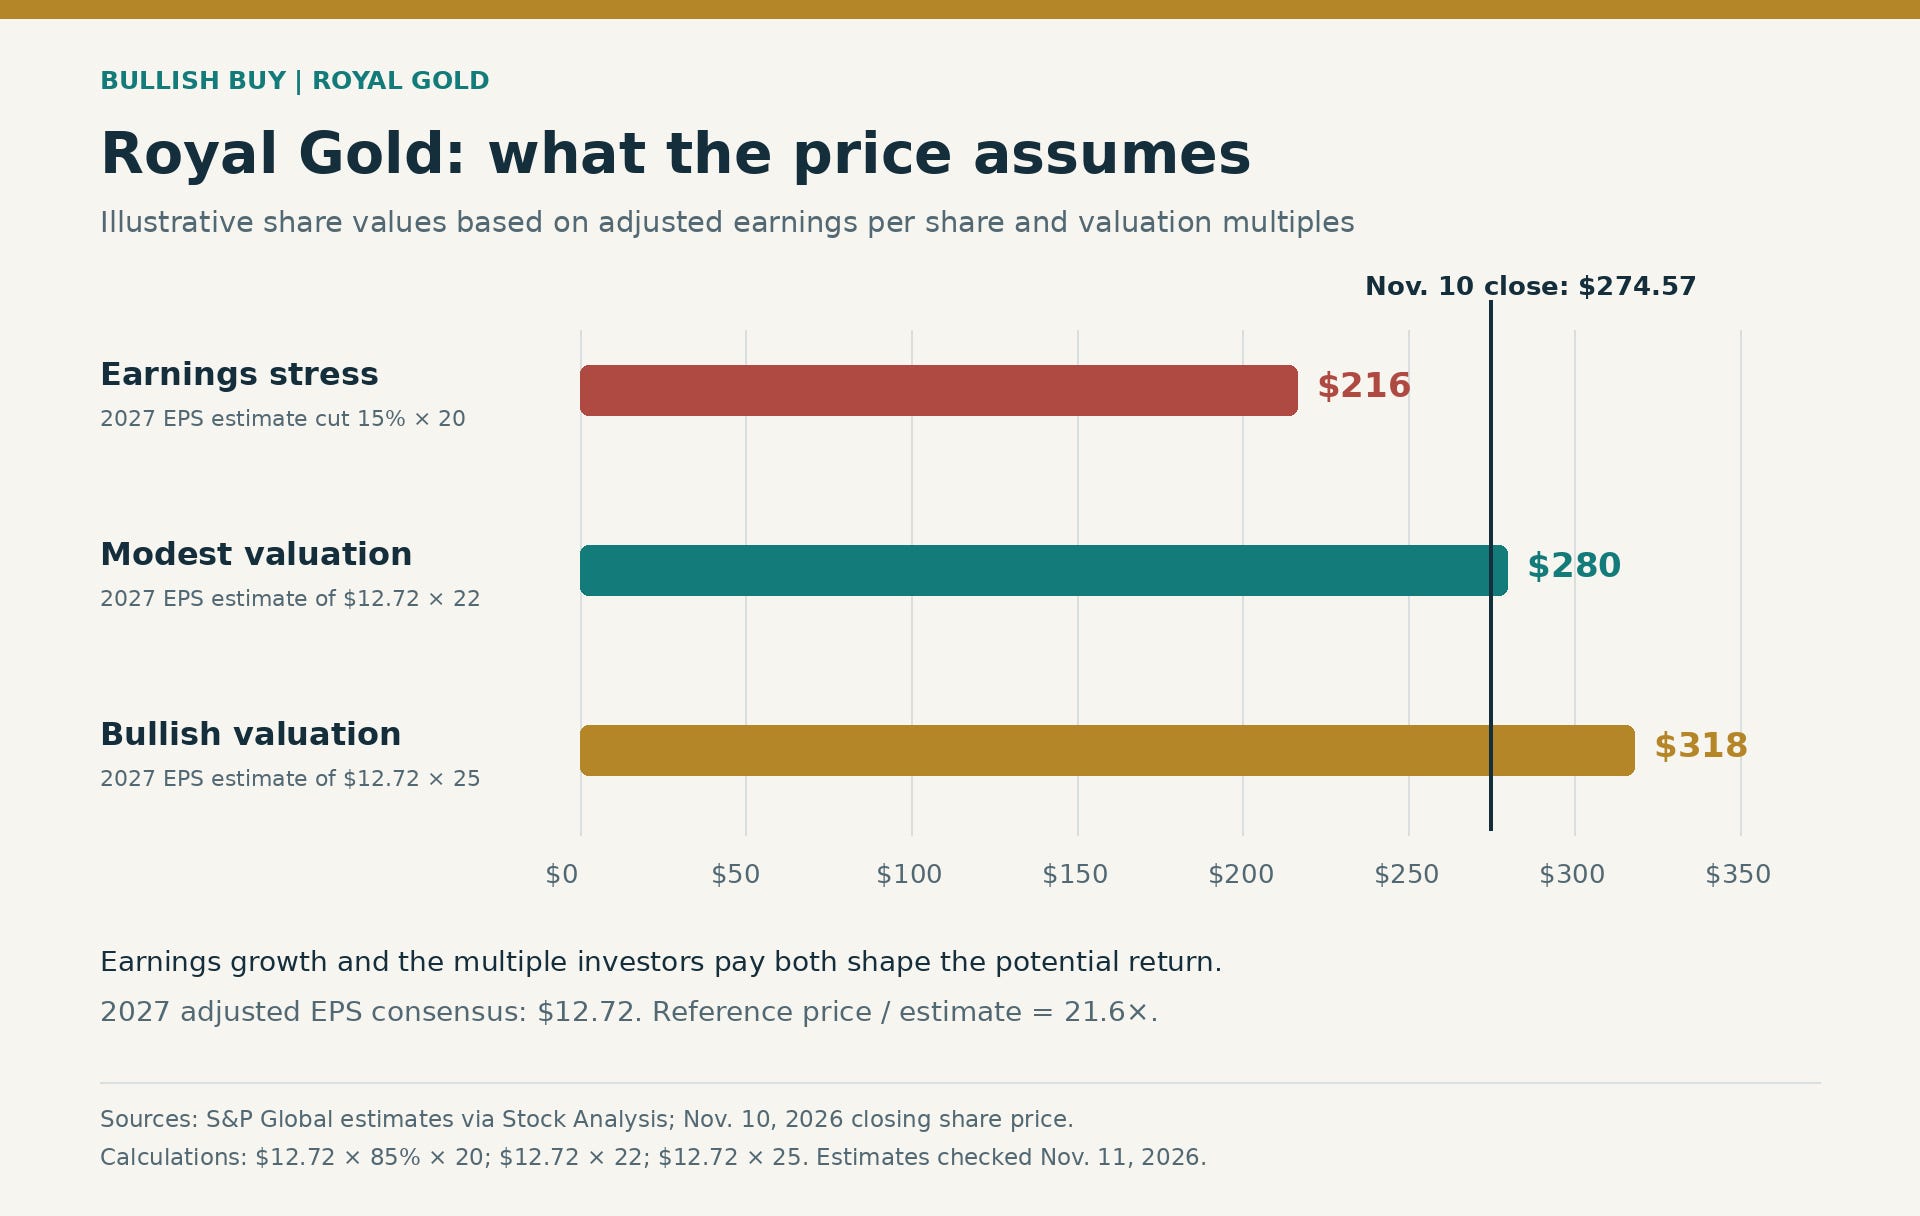
At its Nov. 10 close of $274.57, the shares traded at about 21.6 times the 2027 adjusted earnings estimate of $12.72 a share. S&P Global's forecast implies roughly 19% growth from the 2026 estimate. That offers a more useful yardstick than simply multiplying one strong quarter by four. It also exposes the risk.
If earnings reach $12.72 and investors pay 25 times them, the resulting price would be $318, about 16% above Tuesday’s close. At 22 times the same earnings, the value is about $280, leaving little upside. Yet cut the estimate by 15% and apply a multiple of 20, and the result falls to roughly $216. A good business can still deliver a poor return if its earnings disappoint.
Buy the Cash Flow, Respect the Forecast
The bullish case for buying Royal Gold rests on its acquired assets delivering metal, earnings growth, and cash that no longer needs to retire acquisition debt. It does not require another wave of borrowing or a higher valuation multiple to justify owning a small position. But a sustained drop in metal prices or weaker mine deliveries would challenge that case. Investors should watch earnings estimates as closely as the price of gold itself.
Royal Gold earns a selective buy for patient investors who want equity exposure to precious metals. Starting small leaves room to add more if the price improves. While the debt payoff strengthens the business, it does not remove stock-market risk.
Posting in:
 byUnited States Gold Bureau