
Silver’s selloff gives investors two ways to bet on a recovery: own the metal or buy a miner whose profits could rise faster. Bank of America’s (BAC) $75 silver outlook for 2027 puts Pan American Silver (PAAS) in the spotlight.
The company already generates cash at much lower silver prices. Its battered share price adds another reason to consider a small position before the recovery arrives.
A Recovery With Room to Run
Investing.com reported November 16 that BofA sees silver reaching $75 next year as the pressures from the dollar, oil and interest rates ease. The bank also expects a silver deficit in 2027 after a small surplus this year.
That gives the bullish case a catalyst beyond simply hoping a fallen stock bounces.
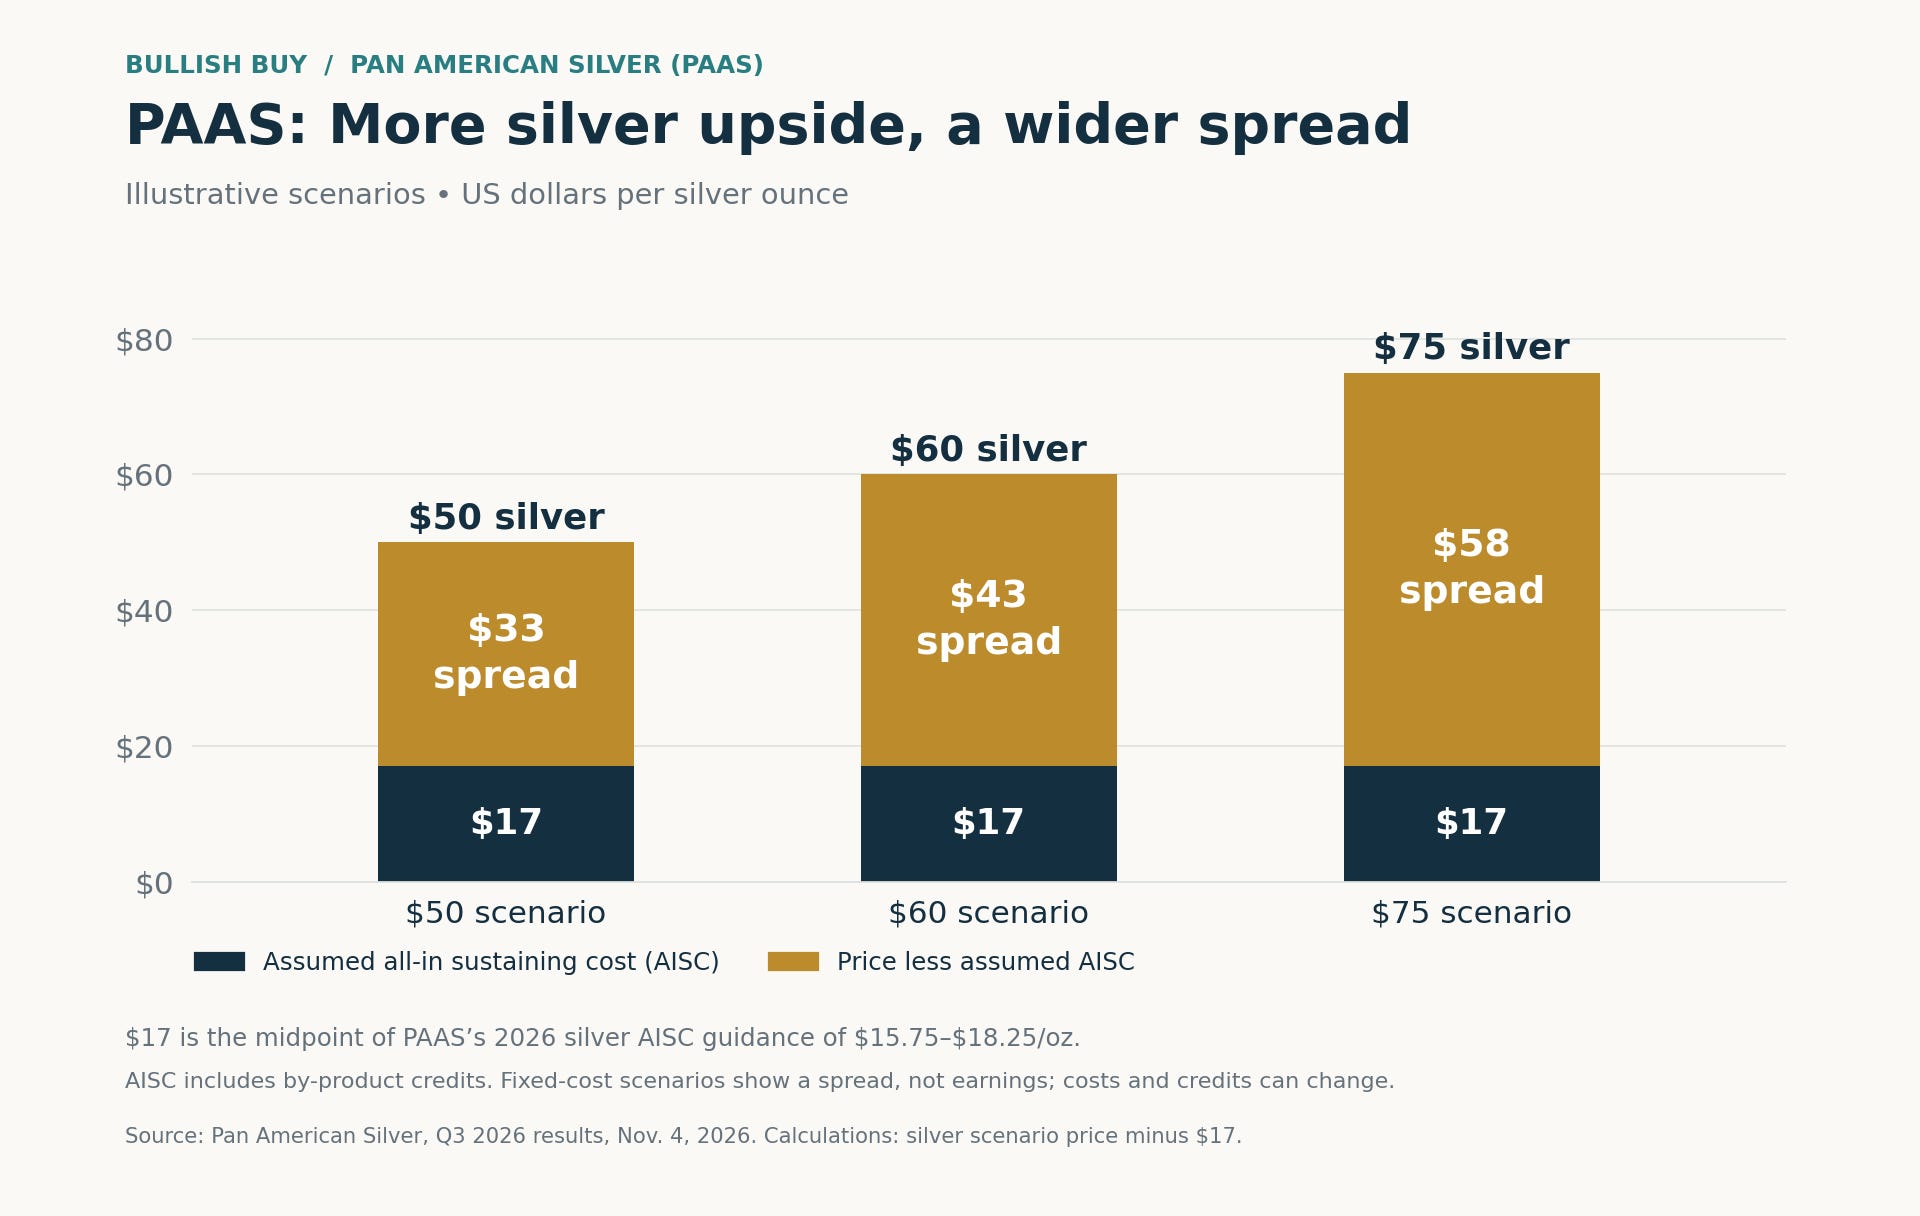
Pan American reported third-quarter silver all-in sustaining costs of $11.21 an ounce. For 2026, it expects costs toward the low end of its $15.75-$18.25 range and production near 25 million ounces.
Those costs include credits from selling other metals. The benefit to shareholders depends on those prices and mining costs as well as silver.
Still, the leverage is substantial. At unchanged annual sales of 25 million ounces, each $10 increase in silver would add about $250 million in revenue before taxes, royalties and other changes. A recovery need not reach $75 to make a meaningful difference.
The Stock Offers a Second Lever
At Monday’s $35.58 close, Pan American traded at about 8.1 times the published 2027 earnings estimate of $4.40 a share, compiled by S&P Global.
If it earns that amount and the stock holds its current multiple, earnings are doing the work. At 10 times estimates, the shares would be worth $44, about 24% above Monday’s close.
There is room for disappointment, too. Even if earnings fall 25% short, today’s price is about 10.8 times that lower figure. The entry price leaves some room for weaker results.
Execution Still Counts
Pan American generated $377 million in attributable free cash flow in the third quarter and returned $300 million to shareholders.
But mine downtime has weighed on silver output, and the company reduced its gold production outlook. Higher gold costs could offset part of silver’s gains.
Our earlier mining-versus-streaming comparison explored how operating expenses reach shareholders. Here, further production cuts, rising costs or sustained weakness in silver would weaken the buy case.
Pan American offers patient bulls a profitable business at a modest earnings multiple. A small initial purchase leaves room to add as operating results confirm the opportunity.
Posting in:
 byUnited States Gold Bureau